

GFM IPO System Breakdown | Liftoff
Liftoff's Return to IPO: Is the Capital Market Buying AI Growth or Platform Valuation Repair? (Institutional Research × Valuation Language Decoding × Market Narrative Analysis)
Introduction: When platform companies retell the AI story, unlike the AI hard infrastructure examples such as chips, energy, power grids, and data centers, Liftoff is more like a necessary comparison in this IPO feature.
It is not the most crucial and scarce underlying link in the wave of AI capitalization; nor is it a deep-tech asset like quantum computing that bets on the technological order of ten years from now. Liftoff is closer to another common but key market phenomenon: an ad tech company with existing revenue, platform capabilities, and a customer base, attempting to regain public market valuation trust through an AI narrative.
These companies don't lack a revenue base, nor do they completely lack technological capabilities. The real question is: for Liftoff, is AI merely a new packaging language, or is it a fundamental driver of incremental growth that can truly change the revenue, efficiency, cost, and profit curves?
This is precisely why GFM included Liftoff in its IPO process analysis. It's not a cutting-edge technology asset, but it represents a potentially more universal issue: as AI spreads from hard infrastructure to platform companies, how can the public market distinguish between genuine incremental growth and mere repackaging?  (Image caption) Liftoff's return to Nasdaq, the starting point of its IPO, symbolizes the platform company's renewed search for public market trust and valuation.
Before proceeding with the analysis, it is necessary to explain the information basis upon which this paper is based.
Liftoff Mobile resubmitted its IPO filing in the United States on April 17, 2026. It had initially filed in January 2026, planning to offer 25.4 million shares at $26 to $30 per share, raising up to approximately $762 million, with a target valuation of up to $5.17 billion. The company planned to list on Nasdaq under the ticker symbol "LFTO". However, due to a sell-off in software stocks, growing market concerns about the impact of AI on traditional software business models, and declining investor risk appetite, the company postponed, withdrew, and adjusted its listing schedule. It subsequently resubmitted the filing confidentially and finally officially filed publicly in April.
Therefore, this article no longer regards Liftoff as a market rumor of "possible return to IPO", but rather as a sample of an ad tech platform that has entered the public market testing window.
From Delay to Restart: A Double Test of Market Sentiment
Liftoff's IPO story itself was a test of market sentiment.
Its initial foray into the IPO market in January 2026 was seen as a representative case of the annual IPO recovery. However, the sell-off of software stocks, market volatility, and investors' cautious attitude towards new stock valuations quickly weakened the conditions for its progress. Postponements, withdrawals, confidential resubmissions, and public resubmissions—this series of actions has exposed the core dilemma of platform technology company IPOs: it's not that they lack business, but rather that the public market will repeatedly scrutinize whether their valuations are truly justified.
The resubmission in April indicates that Liftoff is still looking for a suitable window of market recovery, and also shows that its parent company, Blackstone, still has a strong desire to exit. However, the first delay sent a clear signal: the market remains cautious about this story. A second entry will only bring greater, not less, pressure.
For GFM, Liftoff's institutional value lies precisely in this. It's not a story of "selling the future without revenue," but rather a company with revenue scale, platform data capabilities, and AI technology foundation—but it still needs to answer: Is the public market willing to regain faith in the growth narrative of a mobile advertising technology platform?
What is Liftoff? It's a mobile advertising technology company, not a pure AI company. To understand Liftoff's valuation logic, you must first understand the essence of its business.
Liftoff is an ad technology and monetization platform company serving the mobile app ecosystem. Officially positioned as a growth acceleration platform for the mobile industry, it provides services to advertisers, agencies, DSPs, publishers, and mobile game developers. Its product portfolio includes Accelerate, Monetize, Vungle Exchange, Creative, and Intelligence, corresponding to user acquisition, traffic monetization, programmatic trading, creative optimization, and market insight capabilities, respectively.
This demonstrates that Liftoff is not a narrowly defined AI company, but rather a platform enterprise that embeds AI and machine learning capabilities into mobile advertising, traffic monetization, and creative optimization processes. Its value comes not from a single model, but from the integration of mobile advertising capabilities, user acquisition optimization, publisher monetization, programmatic trading, creative optimization, and market intelligence, coupled with the massive data and model infrastructure that supports all of this.
A more accurate positioning is therefore AI-enhanced platform, rather than pure AI company. This distinction directly determines the framework the market should use to price it. The former needs to demonstrate that AI brings quantifiable incremental benefits; the latter can support its valuation with technological imagination. Liftoff belongs to the former, which is also its fundamental challenge.  (Image caption) The Cortex platform makes 2 billion predictions per second, visually demonstrating how AI is deeply embedded in mobile advertising and real-time optimization.
Is AI just packaging, or a fundamental capability?
Liftoff's AI narrative is not entirely abstract, that must be acknowledged.
An AWS case study published in March 2026 highlighted that Liftoff's Cortex platform performs over 2 billion predictions per second to serve large-scale, real-time mobile advertising. It also noted that migrating some bidding servers from Intel-based architecture to AWS Graviton-based instances resulted in performance improvements and reduced infrastructure costs. Liftoff's official website emphasizes that "AI is in Liftoff's DNA," describing Cortex as a core platform that uses advanced neural network technology to unlock patterns from massive amounts of data and support stronger ad returns. The official release date for Cortex is October 2024.
This is the key context for understanding Liftoff's AI narrative: it didn't suddenly rename its old business to AI in 2026, but rather it has long relied on machine learning in mobile advertising, programmatic delivery, and user matching scenarios, and Cortex is the systematic manifestation of this capability.
The question isn't whether Liftoff has AI, but whether AI is enough to make the market give Liftoff a higher valuation again.
These are not the same thing. If AI merely improves ad delivery efficiency, reduces infrastructure costs, and enhances model accuracy, then it is an important operational tool, but not necessarily the basis for a valuation restructuring. Only when AI can bring new customer structures, new revenue curves, higher gross margins, and stronger platform barriers will the market redefine Liftoff from a traditional adtech company as an AI platform asset.
This is precisely the core question that Liftoff needs to clearly answer in its prospectus and subsequent market communications—not just by saying "AI is in our DNA" in its roadshow presentation slides.
Financial basis: It has revenue, but it is not a risk-free growth stock.
The biggest difference between Liftoff and many deep-tech IPOs is that it already has a clearly defined revenue scale.
According to publicly reported S-1 data, Liftoff's revenue in 2025 was $685.7 million, with a net loss of $23.1 million; in 2024, revenue was $519.3 million, with a net loss of $48.2 million. Revenue is expanding while net losses are narrowing—moving in both directions simultaneously—this is the financial trajectory the public market wants to see.
Based on the data, Liftoff is not just a concept company. It has revenue, a platform, business scale, and signs of improving its losses.
However, the public market doesn't just look at trends; it also questions the underlying quality: Is revenue growth sustainable? Is the growth rate driven by genuine business expansion or a cyclical recovery in the industry? Is the narrowing of losses due to improved operational efficiency or a one-off cost adjustment? Can AI bring higher gross margins, stronger customer loyalty, and a more stable cash flow outlook in the future?
This is the fundamental difference in market pricing logic between Liftoff and infrastructure companies. Infrastructure companies may be revalued by the market due to their scarcity; platform companies, on the other hand, must continuously prove with data that they are not just "old businesses plus AI".
Another crucial financial variable is the IPO prospectus, which previously revealed Liftoff's debt exceeding $1.85 billion. If this debt structure persists in subsequent prospectuses, the use of IPO proceeds will become a key focus for investors: will the funds be used for debt repayment, shareholder exits, technology investment, or business expansion? This will directly impact the market's assessment of the IPO's true nature—is it a corporate financing arrangement or a private equity exit strategy?  (Image caption) The Liftoff SDK reaches 140,000 apps and 1.4 billion daily active users, demonstrating the scale and value of its mobile advertising platform.
Platform valuation recovery: What is Liftoff really selling?
GFM's assessment is that if Liftoff returns to the IPO market, the market will not be buying a simple AI story, but rather a combination of pricing based on three asset attributes.
The first dimension is the mobile app economy gateway. As of September 30, 2025, Liftoff's SDK has integrated with over 140,000 apps, connecting approximately 1.4 billion daily active users and serving over 1,000 advertisers. This means that Liftoff possesses a considerable mobile app reach network, which is itself a valuable asset and exists independently without relying on AI narratives.
The second dimension is the AI-driven ad delivery efficiency engine. With over 2 billion predictions per second, Cortex's ability to continuously improve ad ROI and infrastructure efficiency will be Liftoff's core technological evidence to convince the market. However, the persuasiveness here doesn't come from the technology itself, but from whether AI has changed the platform's unit economics—lower customer acquisition costs, higher ad conversion rates, and stronger customer retention.
The third dimension is the Blackstone background and exit narrative. Liftoff, backed by Blackstone, saw its IPO not merely as a corporate financing activity, but also as a case study of whether private equity assets can exit and be repriced through the public market. Blackstone had considered selling or pursuing an IPO, with valuation targets rising from over $4 billion to as high as $5.17 billion in January 2026. This exit pressure constitutes an undeniable structural driving force behind Liftoff's IPO timeline.
Whether the scale of mobile advertising platforms, AI efficiency engines, and private equity exit windows can work together to support valuation is the real question the market is testing.
Why is Liftoff the "control group" in the AI IPO section?
Unlike Quantum, which sells the option to use technology ten years from now, or power, chip, and data center companies, which stand at the physical bottlenecks of AI expansion, Liftoff is more like a case of platform valuation recovery.
The problem isn't whether the market can imagine the future, but whether the market believes it can turn AI into incremental growth today. This is the core dilemma of the platform-based AI narrative: deep tech companies can sell the future, while platform companies must simultaneously explain the present.
If Liftoff's AI can improve ad conversions, reduce infrastructure costs, improve ROI, increase customer retention, and expand into non-gaming verticals, then it can be redefined by the public market as an AI-enhanced mobile growth platform. However, if AI is merely a repackaging of an existing adtech platform, the market will quickly revert it to the valuation framework of a traditional adtech company.
This is the institutional value of Liftoff as a "control group." It makes the entire IPO study more complete: different types of AI assets face completely different pricing logics and trust structures in the public market. 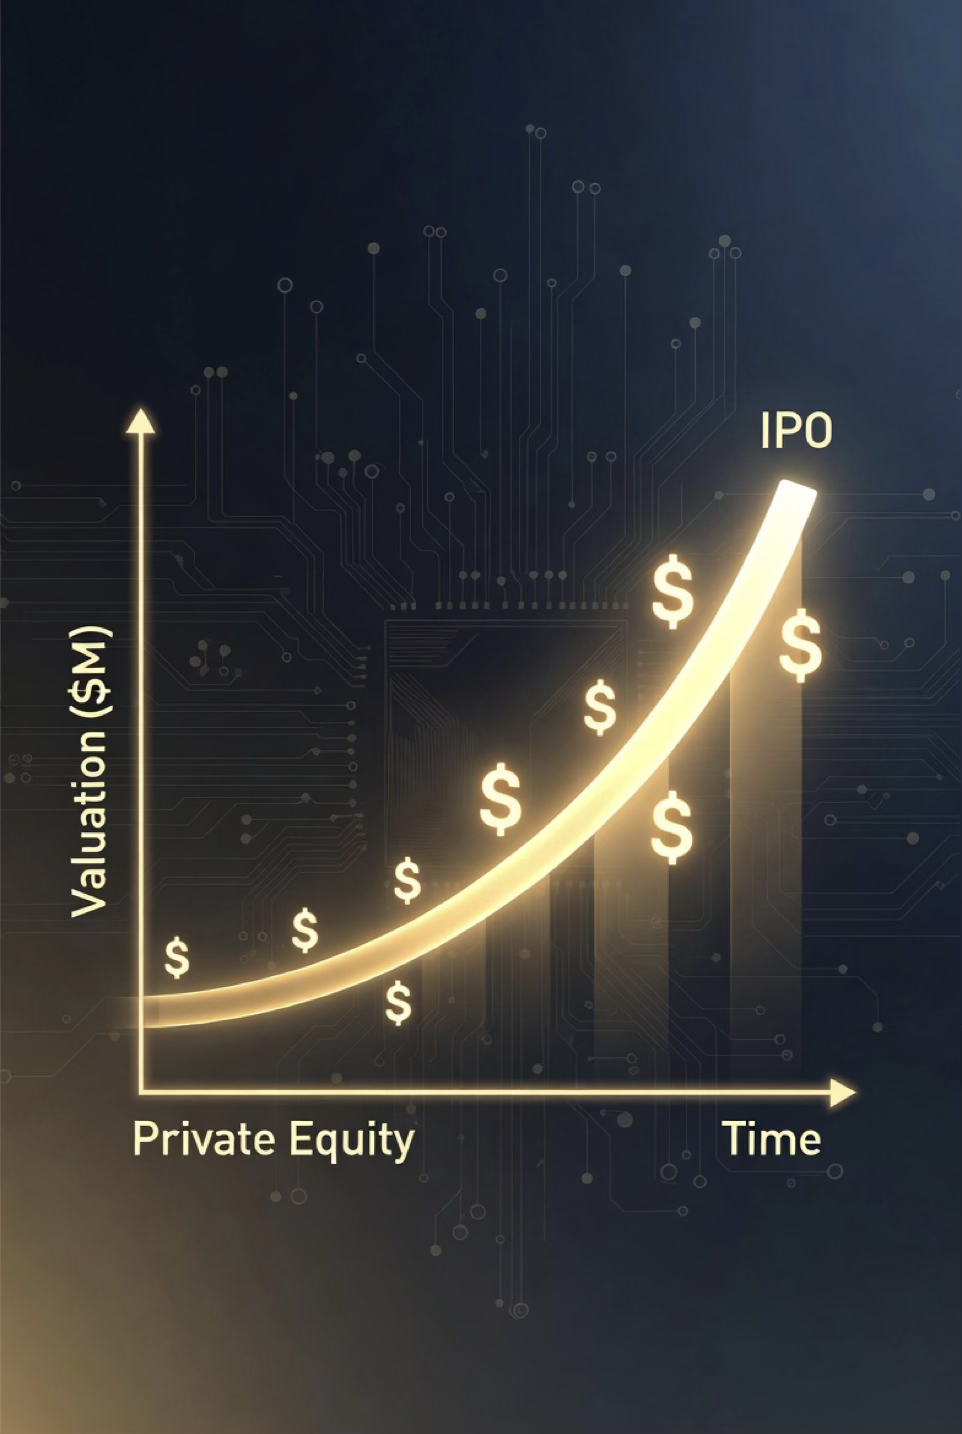 (Image caption) The upward curve from private equity valuation to IPO shows Liftoff's attempt to restore its platform valuation through AI narrative.
GFM IPO Risk Radar: No institutional research should shy away from risk, and this is especially true for Liftoff.
Narrative risk is a primary concern. The most typical risk is rewriting the old advertising technology business into an AI story. Liftoff does have the foundation in AI technology, but the market will demand that it prove that AI is not just a narrative update, but a real improvement in revenue, gross profit, and platform barriers. The stronger the narrative, the more rigorous the financial data in each subsequent quarter will become in terms of whether the narrative can be realized.
Financial risks should not be ignored. While revenue growth and narrowing losses in 2025 are positive signs, Liftoff remains a net loss-making company. If the IPO price was too high, and revenue growth slows after listing, the valuation recovery could quickly turn into valuation compression, and the existing debt structure further limits financial flexibility.
Platform dependency risk is a structural problem for mobile ad tech companies. These companies are highly susceptible to the policies of Apple, Google, the App Store, ad identifier rules, and data usage regulations. Any change in platform policy can have a significant impact on their revenue structure, and these risks are often difficult to predict and hedge in advance.
The risks associated with customer and vertical market concentration should not be underestimated. Liftoff has historically been highly correlated with the growth markets of mobile games and apps. If demand for game advertising fluctuates, growth in non-game verticals falls short of expectations, or a few large clients adjust their advertising strategies, revenue growth will quickly come under pressure.
The risks associated with AI implementation are the core challenge for valuation restructuring. Cortex's technical data is impressive, but investors need to see how AI translates into higher customer ROI, lower customer acquisition costs, higher gross margins, and stronger renewal rates. Otherwise, AI is merely an efficiency tool, not a valuation restructuring engine, and the difference in pricing logic between the two is substantial.
Finally, there is the risk of market window fluctuations. Liftoff has already experienced delays and resubmissions, demonstrating the inherent sensitivity of market windows. When software and platform stock valuations fluctuate, IPO pricing is easily forced to adjust, and the margin for error for a second entry is often smaller than that for the first.  (Image caption) The IPO exit window backed by Blackstone symbolizes how private equity can repric assets through the public market.
Five key disclosures GFM is waiting for
Liftoff's public filings have disclosed some of its financial data, but the following five dimensions remain the focus of GFM's continued monitoring.
Sources of revenue growth: Will revenue growth in 2025 come from more advertisers, more traffic, improved Cortex efficiency, or a recovery in the industry cycle? The quality of growth determines the quality of valuation, and the gap between the two determines the stability of pricing.
The contribution of AI to gross profit and EBITDA: Does Cortex directly reduce infrastructure costs? Does it improve advertising conversion efficiency? Does it improve customer ROI? Whether these contributions can be clearly tracked from financial metrics is key to determining whether the AI narrative has financial support.
Customer structure and industry distribution: What is the revenue share of different vertical markets such as gaming, finance, entertainment, social networking, and e-commerce? Has the non-gaming vertical become a real second growth curve, or is it still just a strategic prospect?
Debt and Capital Usage: Will IPO proceeds go to debt repayment, shareholder exits, technology investment, or business expansion? This allocation directly affects investors' judgment of the nature of the IPO and is key to understanding Blackstone's role in this listing.
IPO Valuation Compared to Peers: If priced close to or above $5 billion, the market will compare it to mobile advertising technology or platform companies such as AppLovin, Unity, Moloco, and InMobi. Liftoff must demonstrate that its AI narrative, growth trajectory, and profit quality are sufficient to support this valuation range, rather than simply relying on its private equity background.
The second battle in the capitalization of AI: a reassessment of the efficiency of platform companies.
The first battle in the capitalization of AI saw the market buying into hard infrastructure: chips, data centers, power, heat dissipation, optical modules, and cloud infrastructure. These assets gained significant market attention due to their scarcity and physical limitations.
The second battle for AI capitalization is underway, with the market beginning to re-examine platform efficiency assets: Who can use AI to transform existing platforms and truly improve the efficiency of traffic distribution, ad matching, user acquisition, and business conversion?
Liftoff is the company that has been put to the test in this second battle. Its institutional value lies in reminding us that not all AI stories are the same asset. Some companies sell the scarcity of hard infrastructure, some sell tickets to future technologies, while platform companies like Liftoff sell the possibility of their valuations being believed in again.
This possibility sometimes holds true, and sometimes it's just a different packaging. The key is whether AI has truly changed a company's product capabilities and cash flow prospects, rather than just changing the narrative language used in roadshows.  (Image caption) Liftoff serves as a control group for AI IPOs, distinguishing between different market pricing logics related to the scarcity of hard infrastructure and the recovery of platform valuations.
GFM's assessment: Is the market buying into AI growth or valuation repair?
GFM's assessment of Liftoff is that if it successfully returns to the IPO market, what the market will really be measuring is not just how much revenue it has, but whether AI is enough to turn a mature platform into a new asset.
There is a clear dividing line here. Simply adding AI to existing businesses only brings short-term relief; adding AI to existing platforms is what supports valuation restructuring; and adding new cash flow curves to existing revenue is the true basis for repricing in the public market.
Liftoff's IPO will test whether there is a genuine connection between these three elements. If the answer is no, it's merely an attempt to repair the platform's valuation; if the answer is yes, it will become a representative case of AI revaluing the efficiency assets of platforms—not only will hard infrastructure benefit, but adtech platforms can also be repriced.  (Image caption) Does AI bring real incremental growth? How does the Liftoff platform translate technology into higher ROI, lower costs, and a stronger growth curve?
Liftoff's real problem isn't whether it can go public, but whether it can regain public trust after going public.
Liftoff's IPO is not a simple story of an "AI company going public".
It's a more sophisticated market test: when an established ad tech platform retells the AI story, does the public market really believe it?
It has revenue, scale, technology, a Blackstone background, and AI infrastructure like Cortex. However, it also faces multiple pressures: competition from the adtech industry, changing platform rules, valuation sensitivity, and repeated scrutiny of its debt structure and AI narrative. The first delay already indicates the market's caution regarding this story; a second entry will only bring greater, not less, pressure.
For GFM, the most noteworthy thing about Liftoff is not "another AI company is going to IPO", but a deeper market signal: after the AI narrative spread from hard infrastructure to platform companies, how can the public market distinguish between real incremental growth and new packaging?
This is precisely one of the most worthwhile issues to analyze in the 2026 IPO market.
Disclaimer: This article is an institutional research piece from GFM's "IPO System Deconstruction" column. It aims to analyze the capital market logic behind Liftoff Mobile's proposed IPO, the valuation language of AI platforms, and the commercialization risks of ad technology. It does not constitute any advice on securities trading, investment recommendations, financing commitments, or invitations to provide listing services.
The information in this article is primarily compiled from Liftoff's official website, SEC EDGAR, Reuters, AWS, Renaissance Capital, TechCrunch, and other publicly available sources. Readers should verify the original sources and consult qualified professional advisors before using, investing in, or making any business decisions based on this article. GFM assumes no responsibility for any decisions made based on this article.