

GFM IPO System Breakdown | Madison Air Solutions
Amid the AI infrastructure boom, an industrial company goes public after deleveraging.
If we only look at the surface narrative, Madison Air Solutions is almost certainly one of the companies most likely to be accepted by the market in 2026.
Standing at the forefront of the AI data center expansion, and providing air management, cooling, and ventilation equipment, it seems like the ideal IPO target that "has real industrial capabilities and hits the hottest theme." Its size is large enough—planning to raise approximately $2.23 billion by issuing 82.7 million shares, priced between $25 and $27 per share, with pricing expected on April 15—to make it a market focus.
But for GFM, what is truly worth analyzing is not whether it benefits from AI, but the institutional nature of this IPO: is it a growth financing or a large-scale deleveraging and capital restructuring using the AI infrastructure boom?
The answer to this question lies in a number that is easily overlooked: Madison Air Solutions currently carries a massive debt of approximately $5.6 billion, and one of the main purposes of this IPO is to repay some of this debt in order to reduce interest expenses and improve cash flow.  (Image caption) The most readily accepted narrative for Madison Air in the market is the increased cooling demand driven by the expansion of AI data centers. However, from a regulatory perspective, the existence of demand does not automatically equate to the company receiving a high valuation based on technological prowess.
I. Who is this company: an industrial integrator, not an AI native company. Stripped of market jargon, the business essence of Madison Air Solutions needs to be explained clearly.
The company develops and manufactures a variety of indoor air quality and air management technologies, applicable to both commercial and residential environments. Its brands include Nortek Air Solutions, Nortek Data Center Cooling, AprilAire, and Big Ass Fans.
It's not a pure technology company that grew from scratch, but rather an industrial systems provider that integrates its brand around air management capabilities. Founded in 2017 by billionaire Larry Gies, it is a subsidiary of Madison Industries.
From a financial perspective, the company’s revenue for the full year of 2025 will reach US$3.3 billion, of which about half of the net sales will come from replacement and upgrade demand, and about 10% will come from aftermarket parts and services, providing the company with a relatively stable cyclical revenue base.
However, in terms of profitability, net profit in 2025 was $124 million, lower than $236 million in 2024, even though revenue increased from $2.62 billion in 2024 to $3.34 billion.
These figures reveal a key structure: revenue is growing, but net profit is declining. This means that cost pressures, integration expenses, or financial costs are eroding profit margins—a common financial pattern for a highly leveraged, acquisition-driven industrial group during its rapid expansion phase.
II. What story does it want to tell: From air management to AI infrastructure, an indispensable part of modern life?
Madison Air Solutions' launch narrative is also divided into three levels.
The first tier: Industrial air management companies. The real revenue pillar. Ventilation, filtration, cooling, and air quality management—this is the actual source of their $3.3 billion in revenue, and also the part most easily priced according to industrial logic.
The second tier consists of data center cooling solution providers. Industry reports indicate that favorable industry trends supporting their growth include an aging housing stock in North America, continued expansion of data centers, and the resurgence of advanced manufacturing facilities. These factors collectively underpin a professional air systems market estimated at $40 billion. The cooling needs of data centers are the core growth driver that companies most hope to gain acceptance from the capital markets.
The third layer is energy efficiency infrastructure in the AI infrastructure era. By packaging air management capabilities as an indispensable supporting infrastructure for the expansion of AI computing power, companies like Madison Air will naturally have the opportunity to obtain higher technology-driven valuations when the market believes that "AI needs not only chips, but also cooling infrastructure."
The question is whether this valuation increase truly stems from an upgrade in the business model, or whether external narratives have simply repackaged traditional industrial capabilities as strategic assets.  (Image caption) Its true business essence remains industrial equipment and air management capabilities, not a pure AI company. This is also the point that the market most easily overlooks, yet should be most reminded of.
III. Deleveraging: The core institutional essence of this IPO. This is the most important part of the entire analysis, and also the part most easily obscured by market propaganda.
The primary purpose of Madison Air Solutions' IPO is to pay off some of its massive debt of approximately $5.6 billion, thereby reducing interest expenses and improving cash flow.
The institutional significance of this statement far surpasses any AI narrative.
This means that Madison Air's IPO is not just about supporting future expansion, but also serves to deleverage, improve its debt structure, and enhance the readability of its balance sheet. This gives the entire IPO a distinct dual nature: part growth financing and part capital structure repair.
The IPO also features a dual-class share structure. Each Class A share has one vote, while each Class B share has ten votes. Upon completion of the IPO, founder Larry Gies is expected to hold approximately 95.2% of the total voting power, thus making the company compliant with the NYSE's "controlled company" governance standards.
This governance structure, combined with the deleveraging motivation, forms a complete institutional picture: the company hopes to complete financing and capital optimization through the public market, while ensuring that the founder's absolute control over the company is not diluted.
For investors, this means purchasing Class A shares, enjoying economic rights, but having extremely limited say in corporate governance. When the founder of a highly indebted company goes public in this way, the market needs to ask more carefully: what is the true return logic behind this investment?
IV. Financial Structure: What do the numbers tell us?
| project | data |
| 2025 revenue | Approximately US$3.34 billion |
| Net profit in 2025 | Approximately US$124 million |
| 2024 revenue | Approximately US$2.62 billion |
| Net profit in 2024 | Approximately US$236 million |
| Total debt size | Approximately US$5.6 billion |
| Planned fundraising scale | Approximately US$2.23 billion (maximum) |
| Issuance of shares | Approximately 82.7 million Class A shares |
| IPO price range | $25 to $27 per share |
| Corresponding market capitalization | Approximately US$12.7 billion to US$13.2 billion |
| Listing Location | New York Stock Exchange |
| Stock Code | MAIR |
| Expected pricing date | April 15, 2026 |
| Founder voting control | Approximately 95.2% |
These figures reveal several structural tensions that need to be addressed.
Revenue grew strongly, from $2.62 billion to $3.34 billion, partly driven by the AprilAire acquisition; however, net profit fell by nearly 50%, from $236 million to $124 million. The significant contraction in profitability despite substantial revenue expansion typically indicates that acquisition integration costs, financial expenses, or operating leverage have not yet been fully realized.
The $5.6 billion debt, compared to the $2.2 billion raised, indicates that even if the IPO is fully successful, the company's leverage structure remains quite heavy. The deleveraging effect is limited, but it can open up new capital market channels for subsequent financing.  (Image caption) Madison Air's foundation lies in its manufacturing, delivery, engineering, and equipment capabilities. These capabilities generate stable cash flow, but do not necessarily translate into high-growth technology valuations.
V. Where is AI? The demand is real, but the barriers to entry still need to be verified.
Madison Air Solutions undoubtedly benefits from the cooling demands resulting from data center expansion. However, it's equally important to ask: what role does AI actually play in its business?
The company's strategy emphasizes AI-driven product innovation, data center cooling business, and after-sales service. However, based on publicly available information, AI is more reflected in product performance optimization and energy efficiency management, rather than constituting some kind of unreplicable underlying technological barrier.
To put it more bluntly, Madison Air's core competitive advantage is more likely to come from its large-scale brand portfolio, deep channel relationships, replacement demand from its huge installed base, and accumulated engineering capabilities in specific vertical scenarios (such as data center cooling), rather than some kind of AI-native technology capability.
The company states in its S-1 filing that its competitive advantages include a trusted brand, deep application-specific expertise, patented innovation, and strong channel and customer relationships. In most markets, the company faces smaller, fragmented competitors; in a few areas, it competes with non-core product lines from large HVAC OEMs.
This self-description itself provides an important clue to its positioning: Madison Air is more like an integrator with scale and brand advantages in the industrial air management field, rather than an AI company with strong technological barriers.
Three scenarios need to be clearly distinguished: is AI a genuine, fundamental differentiating capability; is it a management optimization tool built upon hardware; or is it primarily serving the valuation amplification needs outlined in the prospectus? Based on currently available information, the assessment is that AI truly exists within Madison Air's business, but its actual weight in the revenue structure and competitive advantages still requires further financial and technical details to support its claim.  (Image caption) The AI boom has reopened the market space for these companies. The question is whether the capital market is paying for future growth or revaluing existing assets.
VI. Where are the real risks hidden? Four structural problems Risk 1: Confusion between the purpose of deleveraging and the logic of growth financing.
This is the most critical institutional risk. When an IPO simultaneously serves the dual functions of deleveraging and raising growth capital, investors' expectations of the company can easily become misaligned. If the market primarily interprets this transaction as an "AI infrastructure growth story," ignoring its significant role in capital structure repair, valuation adjustments will be very rapid should growth fail to meet expectations after the IPO.
Risk 2: With a high debt structure, there is limited room for improvement in profitability.
$5.6 billion in debt translates to substantial annual finance costs. Even with strong core business performance, interest burdens will continue to erode net profit. The significant decline in net profit in 2025 may already reflect this structural problem to some extent.
Risk 3: The demand for data center cooling presents an industry opportunity, but industry competition will not be eased as a result.
As "cooling down the demand for AI infrastructure" becomes a hot topic, more suppliers will flood in, and customers' bargaining power may not necessarily decline. Whether Madison Air's growth stems from its genuine competitive advantage or mainly benefits from the overall industry expansion is the most important indicator to continuously monitor after its IPO.
Risk 4: Under a dual-class share structure, external shareholders have extremely limited say.
Nearly 95% of voting control is concentrated in the hands of the founders, leaving external public market investors with virtually no real influence on corporate governance. This structure is relatively common in tech companies, but in a company whose main business model is industrial consolidation and which is burdened with massive debt, the potential impact of governance risks deserves greater attention.
VII. A True Interpretation of the Listing Motives This IPO also includes a concurrent private placement arrangement: Madison Industries Holdings (an entity controlled by founder Larry Gies) has agreed to purchase $100 million of Class B common stock at the IPO price. This portion of shares is not registered under U.S. securities laws, and the underwriters will not receive any related fees.
The implications of this arrangement are worth careful consideration: simultaneous subscription by founders demonstrates confidence in the market and, while ensuring that the control structure is not diluted, also preserves a lower-cost capital entry channel for themselves.
The underwriters lineup is led by Goldman Sachs, Barclays, Jefferies, and Wells Fargo, and also includes Bank of America, Citigroup, and several other institutions. The sheer prestige of this underwriting team is a market signal in itself—the company's operational capabilities in the capital markets are beyond question.
Translated into institutional language, Madison Air's true motivations for this IPO can be summarized in at least four layers: repaying part of its $5.6 billion debt and improving the readability of its financial structure; using the AI infrastructure narrative to revalue its identity from an "industrial integrator" to an "air management technology platform"; completing the public market pricing during the window of greatest market enthusiasm for AI infrastructure; and establishing a public market financing channel for potential future acquisitions and expansions. 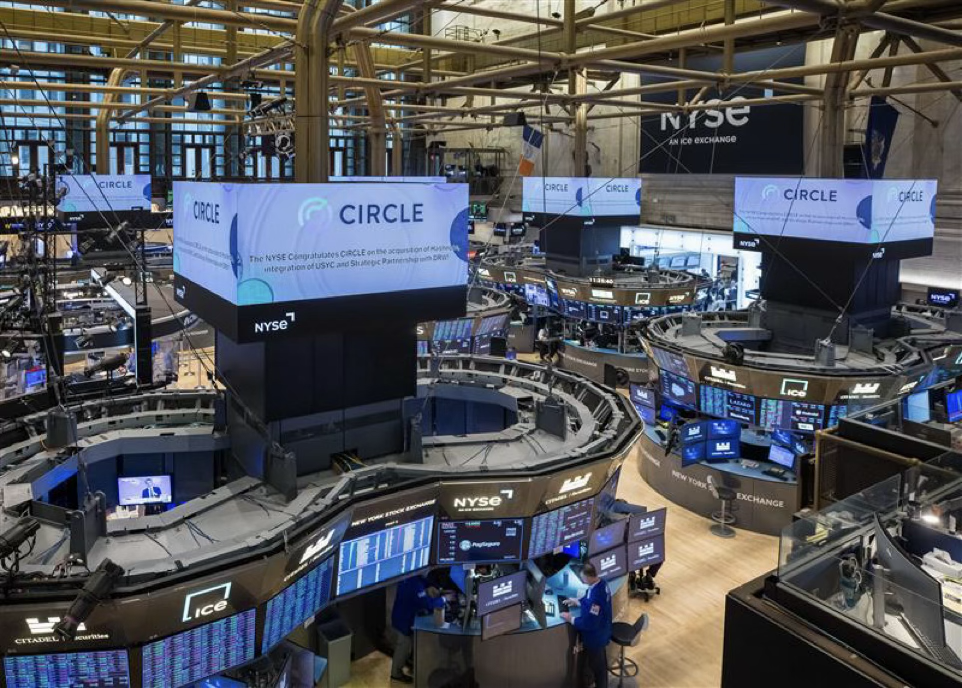 (Image caption) The core of this IPO is not just the listing itself, but rather leveraging the market's enthusiasm for AI infrastructure to complete a round of capital structure optimization.
VIII. Institutional Observations on GFM
Madison Air Solutions reflects not only the new demands brought about by AI data centers, but also how the capital market repackages mature industrial capabilities into popular narratives and uses these narratives to optimize financial structures.
If this IPO is successful, it could become one of the largest US industrial company listings in nearly three decades. This historical significance alone demonstrates its institutional weight far exceeding that of a typical IPO.
It belongs neither to pure technology companies nor to traditional manufacturing, but is a middle-ground asset that is most easily overvalued and misunderstood: it has a real industrial scale, is supported by reasonable industry trends, has a considerable debt burden, and has a clear motivation to reprice itself by leveraging popular narratives.
Such composite IPOs are often most sought after when market sentiment is optimistic because they appear both safe (with revenue, brand, and market presence) and thematically relevant (AI, data centers, energy efficiency). However, when sentiment cools and the market begins to examine financial structures more closely, the restructuring of valuation logic often occurs faster than expected.
There is only one question that truly deserves continued monitoring: Can Madison Air demonstrate in its post-IPO performance that the revenue growth behind its AI infrastructure narrative is a result of real technological and channel capabilities—and not just a successful window of opportunity pricing?
IPO Basic Information
| project | data |
| Company Name | Madison Air Solutions Corporation |
| Stock Code | MAIR (New York Stock Exchange) |
| Core Business | Indoor air quality and air management technologies, including data center cooling |
| Business positioning | Industrial Air Management Platform + AI Data Center Cooling Narrative |
| Major Brands | Nortek Air Solutions, AprilAire, Big Ass Fans |
| 2025 revenue | Approximately US$3.34 billion |
| Net profit in 2025 | Approximately US$124 million |
| Total debt size | Approximately US$5.6 billion |
| Planned fundraising scale | Approximately US$2.23 billion (maximum) |
| IPO price range | $25 to $27 per share |
| Corresponding market capitalization | Approximately US$12.7 billion to US$13.2 billion |
| Founder voting control | Approximately 95.2% |
| Expected pricing date | April 15, 2026 |
| lead underwriter | Goldman Sachs, Barclays, Jefferies, Wells Fargo, etc. |
The above data is sourced from SEC filings, Bloomberg, Renaissance Capital, and other publicly available information. It is for research purposes only and does not constitute investment advice.
This article is a GFM institutional observation and does not constitute any investment advice. GFM focuses on the institutional logic, narrative structure, and valuation language behind IPOs, recording market judgment samples that can be cited and tracked over the long term.
GFM's "IPO" column | Institutional Research × Decoding Valuation Language × Market Narrative Analysis
Global Finance Media Group — gfm.news